 comparison
Home Inspection vs Home Appraisal for Buyers Explained
Last Updated: October 29, 2026
Quick Summary
A home inspection assesses the physical condition of a house, while a home appraisal estimates its market value for the lender. An inspection tells you what you are taking on, and an appraisal confirms the price is supported.
- An appraisal protects the lender and does not check the roof, foundation, electrical, or plumbing for defects.
- A standard home inspection takes 3 to 4 hours, and larger homes or crawl spaces take longer.
- Your inspection and appraisal contingency deadlines are separate, so track both dates in your contract.
- Sort inspection findings into safety hazards, major defects, and routine maintenance before deciding how to respond.
- A low appraisal may be resolved by renegotiating the price, paying the gap in cash, or challenging the appraisal.
Table of Contents
- Why Buyers Mix Up Inspections and Appraisals
- What a Home Appraisal Is and Who It Protects
- What a Home Inspection Is and What It Covers
- Side-by-Side Comparison: Purpose, Who Orders, Who Pays, Who Performs
- How Long Each Takes and How It Fits Your Buying Timeline
- What to Do With Inspection Findings and a Low Appraisal
- Reading a Home Inspection Report Example and Booking Your Inspection
- Frequently Asked Questions
Why Buyers Mix Up Inspections and Appraisals
Home inspection and home appraisal sound alike, and both show up in the same stretch of a home purchase. That's why buyers often assume one covers what the other does. It doesn't. The two services answer different questions, and confusing them can leave you with gaps you didn't know existed.
A home inspection is a visual, non-invasive review of the property's physical condition. An appraisal estimates what the home is worth. One tells you what shape the house is in. The other tells your lender whether the price makes sense.
What a Home Appraisal Is and Who It Protects
An appraisal is an estimate of a home's market value, usually ordered by the lender. The appraiser compares the property to recent sales of similar homes nearby, often called comparable sales, and adjusts for differences in square footage, lot size, and features. The result helps the lender confirm the loan amount matches the home's value.
Here's the key point for you as a buyer: the appraisal protects the lender, not you. It doesn't check the roof, foundation, electrical system, or plumbing for defects. An appraiser may note visible condition issues, but that isn't the purpose of the report.
What a Home Inspection Is and What It Covers
A home inspection looks at the physical condition of the house. The inspector evaluates the major systems and structure, including the roof, foundation, heating and cooling, electrical, and plumbing, and documents safety hazards, major defects, and routine maintenance items.
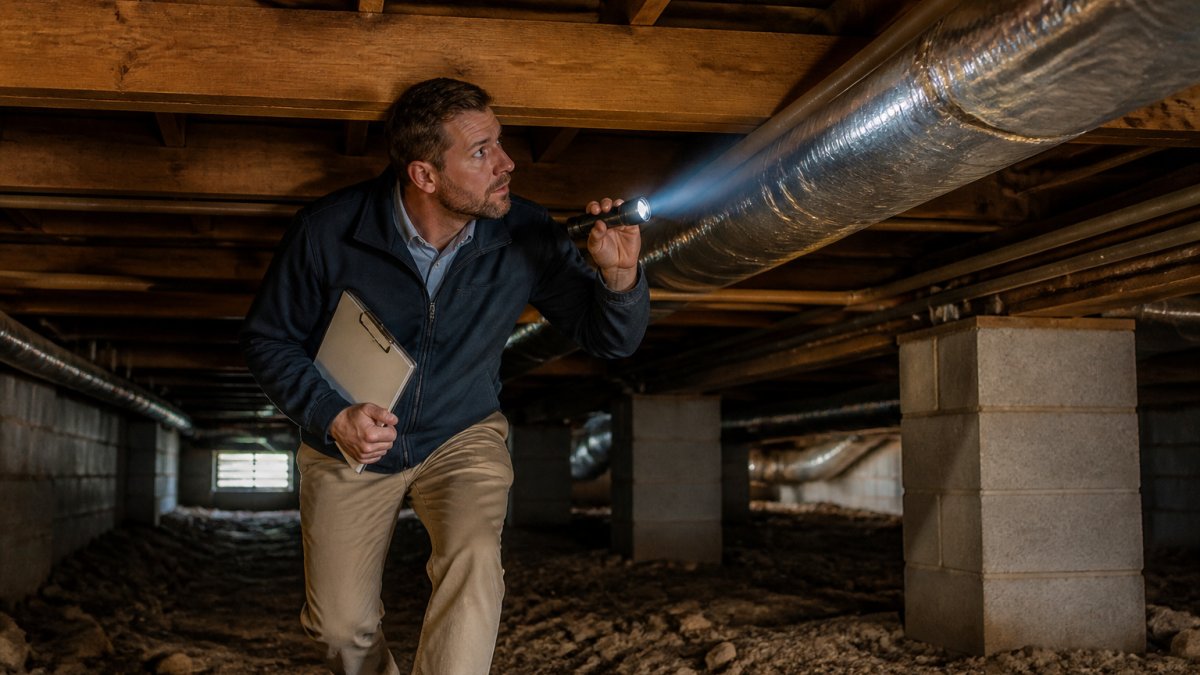
A standard inspection at our company takes 3 to 4 hours, since every system needs a proper check. Larger homes, crawl spaces, or properties with significant issues take longer. Standard inspections are visual and non-invasive, so specialized testing such as radon or mold assessment is handled separately. Integrating these additional evaluations into a single visit through combined building inspections ensures that potential structural and pest-related concerns are identified simultaneously.
Your inspection report is a decision tool. A useful report is a prioritized punch list rather than a long narrative, so you can quickly see what's a safety concern, what's a major defect, and what's routine upkeep.
Side-by-Side Comparison: Purpose, Who Orders, Who Pays, Who Performs
Both services happen during a purchase, but their roles differ. The table below summarizes the differences.
| Factor | Home Appraisal | Home Inspection |
|---|---|---|
| Main purpose | Estimate market value | Assess physical condition |
| Who orders it | Usually the lender | Usually the buyer |
| Who pays | Typically the buyer, collected at closing | Typically the buyer |
| Who performs it | Licensed or certified appraiser | Licensed home inspector |
| Protects mainly | The lender | The buyer |
| Key question answered | Is the price supported? | What condition is the home in? |
Notice the "who pays" row. In many transactions, buyers cover both costs, but the appraisal fee is tied to the lender's requirements, while the inspection is a service you choose to protect yourself. Confirm the exact fees with your lender and your inspector, since costs vary.
Independence matters here too. We work for the client, not for any real estate agent. Our role is an objective report so you can decide with clear information, not to help close a deal.
How Long Each Takes and How It Fits Your Buying Timeline
Timing is where many buyers get caught off guard, because the inspection and the appraisal run on two different clocks, and both are tied to deadlines in your contract. Miss one and you can lose your leverage to negotiate or walk away.
Here is the sequence most buyers see after their offer is accepted:
- Inspection period opens. Your contract sets an inspection contingency window, often a set number of days from acceptance. This is your window to inspect, review the report, and decide whether to ask for repairs or credits, renegotiate, or terminate under the contingency.
- Inspection happens early in that window. Schedule it in the first few days so you have time to read the report and act before the deadline. A standard inspection takes 3 to 4 hours on site. We aim to deliver most reports the same day or the next day, and for most standard residential inspections, expect the report by late evening on the second business day. Expedited same-day reports are available if you request one at booking. Larger homes, crawl spaces, or properties with significant issues take longer, and the inspector will tell you directly.
- Appraisal is ordered by the lender. The appraisal usually runs on its own timeline set by the lender and your loan terms, and the result gates loan approval. It often happens around the same stretch as the inspection but is not part of your inspection contingency.
- Contingency deadlines close. Your inspection contingency and your appraisal contingency (if your contract has one) each have their own deadline. Know both dates and which decisions they lock in.
A few practical points that save buyers trouble:
- Read your contract's contingency dates before you schedule anything. The inspection window and the appraisal window are separate, and one does not extend the other.
- Do not wait until the last few days of the inspection period. If the report raises questions, you may want a specialist evaluation, pest, sewer, roof, structural, radon, or mold, and those take time to schedule. A clean general inspection does not mean specialized testing is unnecessary.
- Ask your lender when the appraisal is ordered and when the result is expected. That date matters if you are relying on an appraisal contingency.
- Keep your own calendar. Write down the inspection contingency deadline, the appraisal contingency deadline (if any), and the financing deadline. These are the dates that decide what options you still have.
In East Tennessee, crawl spaces, humidity, and drainage and grading issues are common enough that buyers in Knoxville and Knox County, and in Blount, Anderson, Loudon, Sevier, Jefferson, and Union counties, often benefit from scheduling the inspection right away so there is room for a follow-up look if something needs it.
The easiest way to get started is to get a quote online.
What to Do With Inspection Findings and a Low Appraisal
Sometimes the two reports point in different directions. An inspection might reveal a costly issue, or an appraisal might come in below your purchase price. Each situation calls for a different response, and the earlier you understand your options, the more control you keep.
When the inspection finds problems
Start by sorting the report into three buckets: safety hazards, major defects, and routine maintenance. That order tells you what actually needs to be resolved before closing versus what you can plan for later.
From there, buyers generally have three paths:
- Ask the seller to make repairs. Common for safety items and clear defects, but you are relying on the seller's contractor and the quality of the work. If you go this route, ask for documentation of what was done.
- Request a credit or price reduction. Often simpler than repairs, because you control how the work gets handled after closing. This is where a prioritized report helps, it lets you point to specific items rather than a vague list.
- Back out under your inspection contingency. If the issues are severe enough or the seller will not move, the contingency may let you terminate within the deadline. This is why the deadline matters.
Choose based on severity and your budget, not on emotion. A report organized as a punch list makes the conversation with your agent and the seller far more productive. And remember: we do not perform repairs and never quote repair work. We give you the information so you can decide.
When the appraisal comes in low
A low appraisal is not automatically a dead deal. Before you decide whether to skip an inspection to save money, see the real cost of ignoring inspections. You have several options, and which ones are available depends on your contract terms:
- Renegotiate the price with the seller. If the home appraised below the agreed price, the seller may agree to come down rather than lose the sale.
- Pay the difference in cash. You can cover the gap between the appraised value and the purchase price, though this raises your out-of-pocket cost and changes your loan-to-value picture.
- Challenge the appraisal. If you believe the appraiser missed relevant comparable sales or made an error, your lender can explain the reconsideration process. It is not a guarantee of a change, but it is worth asking about when you have solid evidence.
- Walk away if your contract allows. If you have an appraisal contingency, it may give you an exit within its deadline.
Talk with your lender and your agent early, because appraisal timelines are tight and the contingency deadline can arrive quickly.
The bigger picture
An inspection and an appraisal answer different questions, and neither replaces the other. A home can appraise at the purchase price and still have a failing HVAC system or a leaking crawl space. Use both reports together: the appraisal tells you whether the price is supported, and the inspection tells you what you are actually taking on. That combination is what lets you negotiate with confidence, plan for what comes next, or walk away knowing you made an informed call.
Ready to get the condition side of the picture? The easiest first step is to get a quote online.
Reading a Home Inspection Report Example and Booking Your Inspection
A useful report is short enough to act on. Compare home inspection reports side by side with a checklist that helps you spot red flags and prioritize findings.
We recommend joining us for the summary at the end of the inspection rather than attending the full inspection itself.
Ready to get started? The easiest first step is to get a quote online. Pricing depends on the home's age, square footage, location, and any additional services.
Frequently Asked Questions
Is a home inspection the same as an appraisal?
No. A home inspection evaluates the physical condition of the property, including the roof, foundation, HVAC, electrical, and plumbing, and documents defects and safety concerns in a written report. A home appraisal estimates the property's market value, usually for the lender, by comparing the home with recent sales of similar properties. Buyers often need both, but they answer different questions: an inspection asks what condition the home is in, while an appraisal asks what the home is worth.
Does a mortgage lender require an appraisal?
In most mortgage transactions, yes. The lender orders the appraisal to confirm that the home supports the loan amount, which protects the lender if the buyer defaults. The buyer usually pays for the appraisal as part of closing costs, but the report belongs to the lender's decision process. An appraisal does not tell the buyer whether the roof, foundation, or electrical system is sound, so a buyer who relies only on the appraisal may still face costly surprises after closing.
Can a home inspection affect the appraisal?
Indirectly, yes. An appraiser evaluates value based on the home's condition, features, and comparable sales, so a home with visible deferred maintenance may be valued lower than a similar home in good shape. The inspection and appraisal are separate reports with separate purposes. Buyers should not expect one to replace the other, and an inspection report can help a buyer decide whether to negotiate repairs or credits if the appraisal comes in below the purchase price.
What should buyers do after receiving a home inspection report?
Read the report as a prioritized list. Separate safety hazards and major defects from routine maintenance items. Ask the inspector follow-up questions about anything unclear, and consider specialists when the report recommends them. Use the findings to decide whether to request repairs, ask for a credit, adjust the price, or walk away within your contract's inspection contingency period. Many buyers also upload the report to an AI tool to help summarize items and draft questions, then book a short follow-up call.